Refinance Calculator AU
How to prepare and compare a home loan refinance
Record the loan you have now
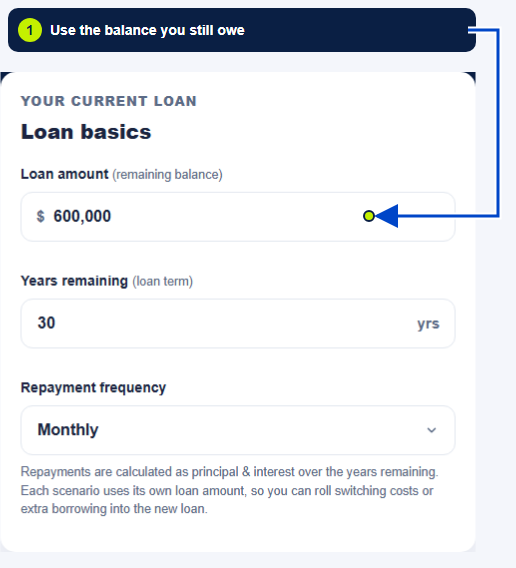
Use a recent statement to record the outstanding balance, rate, remaining term, repayment frequency and recurring fees. List any offset or redraw facilities you rely on separately. The original loan amount and original 30-year term may no longer describe your current position.
Compare a new offer with staying put
Replace any illustrative calculator rate with the rate in the offer. Check the ongoing fees, offset access, redraw rules and restrictions. A smaller repayment alone does not establish a lower overall cost.
Price the change before you apply
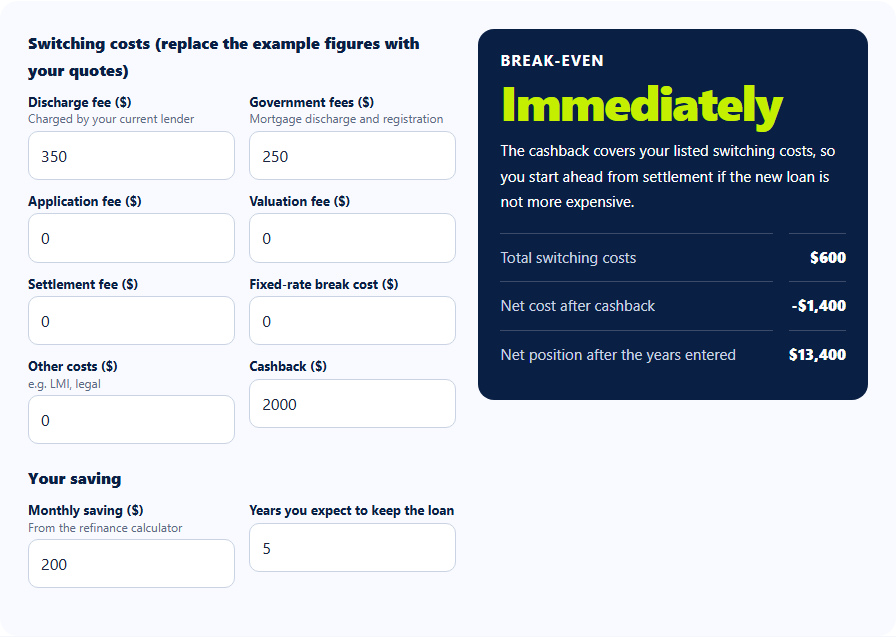
Request discharge, application, valuation, settlement and government charges. If you are leaving a fixed term, request a dated break-cost quote. Ask whether lenders mortgage insurance applies to the proposed borrowing. Enter costs once and count cashback only when its conditions can be met.
Prepare the application and check settlement
Read the approved loan documents and repayment schedule before accepting. Coordinate the discharge and settlement process with the lenders or broker. After settlement, verify the old loan has closed, the new balance is correct and the repayment instructions work. Check linked accounts before cancelling anything.
A comparison that keeps the decision clear
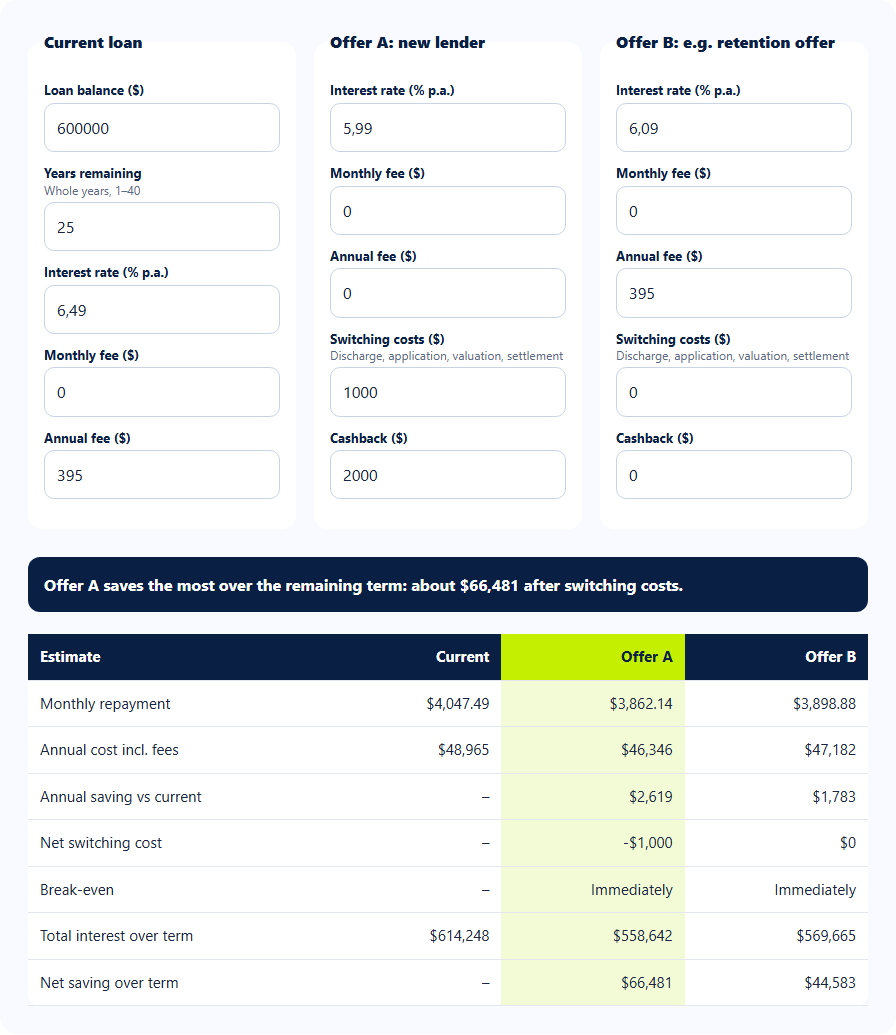
For an illustrative $600,000 balance with 25 years remaining, start by comparing both offers over 25 years. If another quote uses 30 years, keep that as a separate scenario: its lower repayment may come from the longer repayment period. The main calculator does not model two different remaining terms in one comparison.
Sources and calculator limits
Continue exploring
Where will your next move take you?
Calculators and practical guides
Compare your current loan with a new loan, including repayments, fees and payoff time.
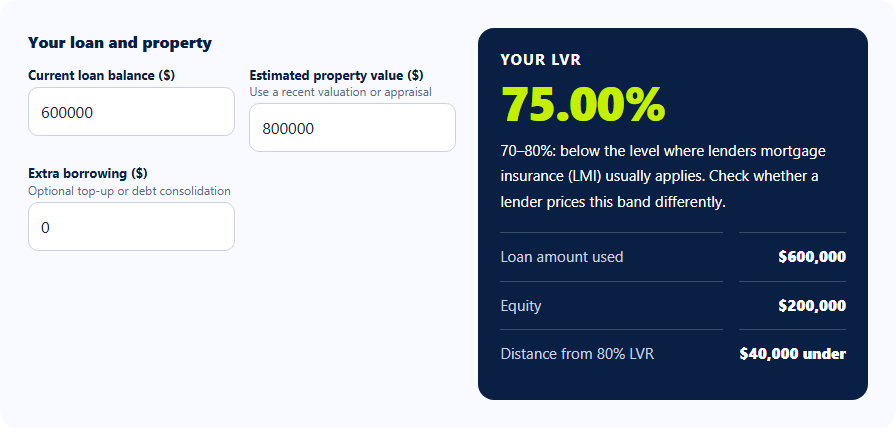
Work out your loan-to-value ratio, equity and distance from 80% LVR.
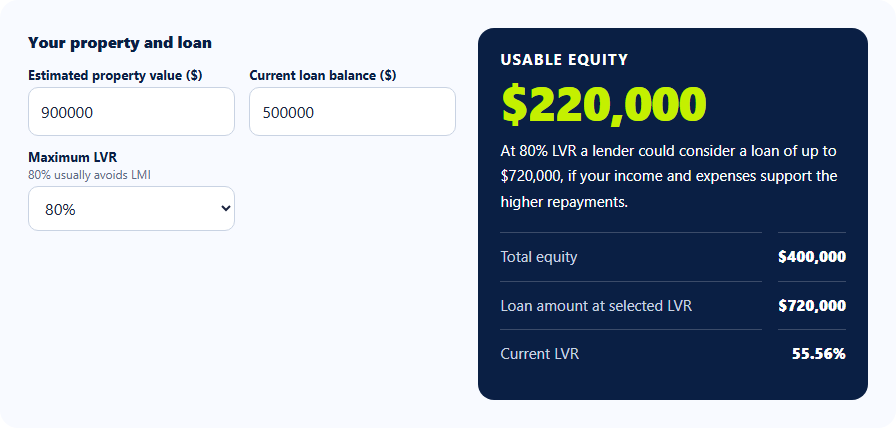
Estimate your usable equity and the loan amount at your chosen LVR.
Compare two offers against your current loan, including fees and cashback.
Add up switching costs and estimate how long your savings take to cover them.